A wonderful invention. An unfortunate investment.
Progress and investment returns are different propositions.
01 / A principled commitment to other people's disruption
Imagine a boardroom in which everyone believes in creative destruction. It has been excellent for the companies down the street. Their employees have become more adaptable, their offices more available, and their difficulties a useful illustration of the market's capacity to allocate resources. Then someone advances the presentation to a slide about this company. The room's commitment to economic renewal remains absolute, although several directors now feel the transition should be managed responsibly.
This is an invented room. You may nevertheless recognize the furniture.
Two books help establish that problem. In Capitalism in America, Alan Greenspan and Adrian Wooldridge put creative destruction at the center of American economic development: productive renewal depends on shifting resources toward better uses. Their introduction also acknowledges displacement, speculative excess, and the tendency of successful challengers to become defenders of the status quo. It is a history with an argument, not a guarantee that every disruption is beneficial or that every financial claim deserves protection.1
Niall Ferguson's The Ascent of Money makes a complementary case for the historical importance of finance itself. Credit, investment institutions, and financial arrangements are part of how societies accomplish large things, not merely a parasitic commentary on those things. His accompanying 2009 lecture explores financial evolution, including institutional failure and the dangers of indefinitely preserving financial giants. The two perspectives belong in conversation; neither supplies a date for the next crash.23
There are three different claims hiding inside the sentence “this changes everything.” The technology will matter. A particular business will capture some of the value. The security being sold today will reward its purchaser at today's price. Each might be true. None makes the next one automatic. The work of a boom is often to persuade us that distinguishing them shows a disappointing lack of vision.
Admire the machine. Read the terms of the security separately.
02 / The trains were real
Start with a railroad. Not a stock certificate depicting a railroad. An actual line: grading, bridges, rails, rolling stock, stations, maintenance, workers who understand what happens when heavy things move quickly. There is a physical achievement here that no subsequent financial embarrassment can erase. A locomotive does not become less impressive because somebody financed it badly. It also does not become more solvent because it is impressive.
The Federal Reserve's historical account of the Panic of 1873 describes railroad investment running ahead of demand for new capacity. European selling of American securities worsened financing conditions. Companies could not obtain cash for operations or refinance maturing debts. Jay Cooke & Co., heavily exposed to railroads, failed in September. Loss of confidence spread beyond the original investments. This was a financing crisis around economically consequential infrastructure, not the discovery that transportation had been an elaborate hoax.4
The train keeps running after the bond fails. A new owner might buy the assets cheaply, carry less debt, and operate a respectable business on the remains of somebody else's investment. The first owner was right about the usefulness of transportation. The second owner was fortunate enough to buy after that conviction had become much less expensive.
The historical analogy has limits. A nineteenth-century railroad and an AI service have different cost structures, competitive environments, useful lives, regulations, and sources of funding. Today's largest technology companies are not interchangeable with speculative railway promoters. The point is not that the same photograph will develop again. It is that a genuine improvement in human capability does not settle the economics of every project undertaken in its name.
The train may leave the station. Your capital need not return on it.
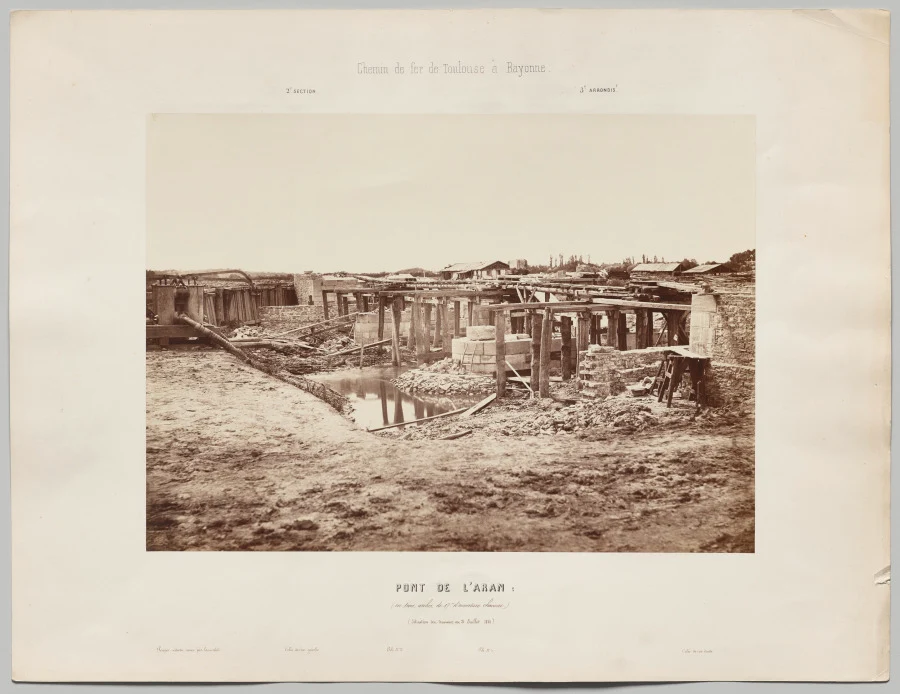
The work between the drawing and the railway. A French construction record, not an image of the American Panic of 1873.
Édouard Baldus, Pont de l'Aran: construction progress, July 21, 1861, 1861. Cleveland Museum of Art · Gift of Michael Mattis and Judith Hochberg · CC0. Collection record ↗03 / Three clocks, one slide
To understand a technology boom, put three clocks on the wall. The first measures technical progress: how quickly the invention improves. The second measures adoption: how quickly customers can reorganize their work around it. The third measures financing: how long the company can meet its obligations before it needs more money. A good pitch deck makes the hands look synchronized. A real business has to cope when they are not.
Consider an imaginary manufacturer adopting a useful AI inspection system. The prototype spots defects. The demonstration is convincing. But the factory must integrate cameras, change procedures, teach supervisors when to override the system, document failures, and decide who signs off when machine and human disagree. The capability arrived before the institution that can use it. There is work between the demonstration and the income statement, and most of it does not wear a conference badge.
Economists Erik Brynjolfsson, Daniel Rock, and Chad Syverson describe a related mechanism in their research on the productivity J-curve: general-purpose technologies require complementary investment, including intangible organizational work. Resources go into building those complements before their benefits fully appear in measured output. It is a reason for patience about adoption, not a license to assume that every delayed return will eventually materialize.5
Suppose our manufacturer needs eighteen months to deploy the system. The vendor has nine months of cash. Its investors expect a new round in six. Its compute provider needs to be paid every month. Everyone can agree the product is useful and still end up in a highly practical argument about who is financing the twelve months that enthusiasm has omitted. The technology clock does not stop because the money clock rings.
In the imagined boardroom, the clocks are represented by a single ascending arrow. This saves space. It also saves everyone from discussing the fact that the lender owns the alarm.
Capability
When the technology can perform the task.
Adoption
When the customer can put it to work.
Financing
When the obligations must be paid.