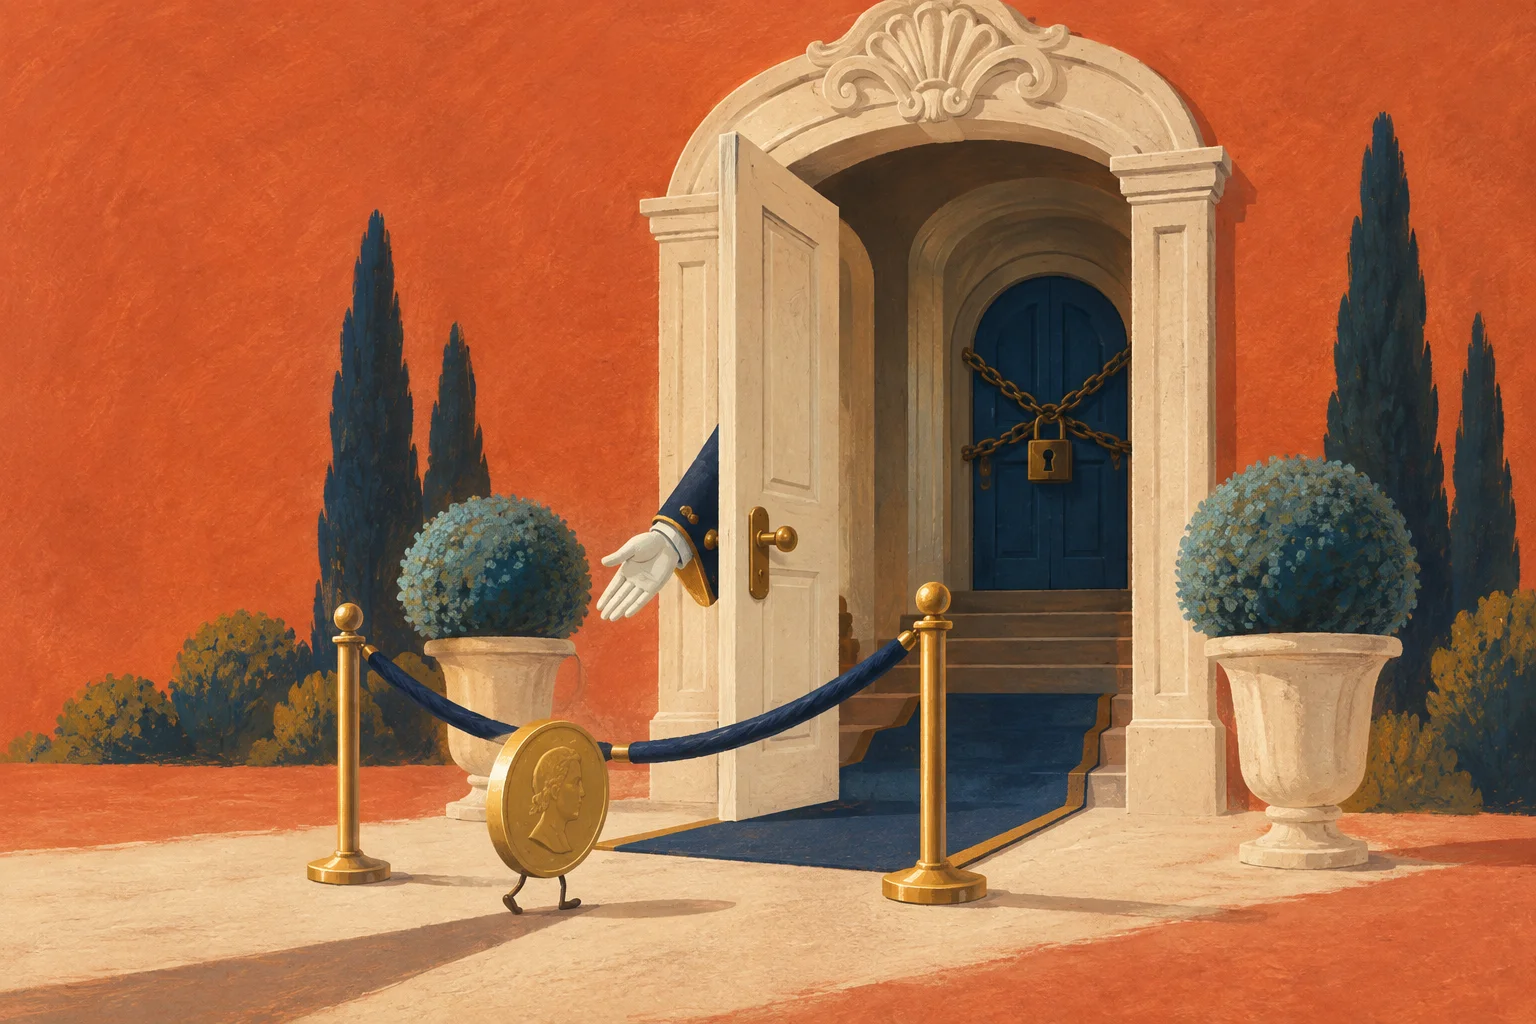
The most powerful word in private-market marketing is not “return.” It is “access.” Return requires waiting. Access can be felt immediately.
USVC markets access to venture investments through a fund structure. Its website also carries important qualifications: prominent companies associated with the broader AngelList ecosystem are not automatically evidence of a particular USVC holding. The fund documents page states that shares are illiquid, have no public trading market, and depend on discretionary repurchase offers rather than guaranteed liquidity.12
The qualifications are right there in the disclosures. Reading them produces a different sensation from being invited past a velvet rope, which may explain the relative marketing budgets.
The door and the thing behind it
A wider doorway can be a genuine improvement. There is no obvious virtue in making a financial opportunity difficult to reach merely because it has historically been difficult to reach.
But easier entry does not transform the underlying asset. If an investment depends on uncertain future outcomes and may take years to realize value, a polished interface cannot remove that character. It can explain it well or badly. It cannot redesign time.
This is a reading of the sales language, not a product recommendation. Suitability depends on the investor’s circumstances and the full terms. Membership has no opinion about whether you can afford to wait.
Famous neighbors are not your address
The analytical work is to identify the exact relationship. Does the fund own a company directly? Hold an interest through another vehicle? Refer to an adviser’s wider history? Illustrate a category? Those are different statements, even if they use the same logo.
Follow the logo to the actual holding. A familiar company name can appear on a page for several reasons; only the documents tell you which relationship you are buying.
The same applies to a historical track record. A record belongs to a defined manager, strategy, period, and set of investments. It is not an atmosphere that transfers automatically to everything arranged nearby.
Illiquidity has poor onboarding metrics
Waiting is hard to sell elegantly. “You may not be able to exit when you want” does not improve the conversion funnel, but it may be central to the investment.
The feeling of control matters. A balance displayed on a screen is not necessarily an immediately realizable amount. An estimate of value is not the same event as a transaction. A mechanism for requesting liquidity is not a promise that a request will be satisfied.
USVC’s disclosures say as much. The glamorous word at the entrance and the conditions governing departure belong in the same reading session.
Membership is not an investment thesis
The cultural pitch of exclusive markets is that other people have been getting something you were denied. Sometimes that is a fair complaint about opportunity. Sometimes it is a remarkably efficient way to make scarcity feel like evidence of quality.
A restaurant can be difficult to book because it is excellent. It can also be difficult to book because it has six tables. The waiting list does not tell you what dinner will taste like.
Similarly, private status does not establish that an asset is superior to a public alternative, suitable for a particular person, or attractively priced. Those questions survive the removal of the velvet rope. Indeed, wider participation makes clear explanations more important.
Before enjoying the entrance, check whether the door opens from the inside.